Weekly Review & Indian Stock Market Prediction (Sep 28th – Oct 02nd, 2026)
Nifty declined 0.88% WoW to 23,140.50, extending losses for the seventh consecutive week amid crude oil volatility, elevated global yields and FII selling. Coal India, ITC and Eternal gained, while Bharti Airtel, Trent and Infosys declined. Full recap & outlook for September 28–October 2.
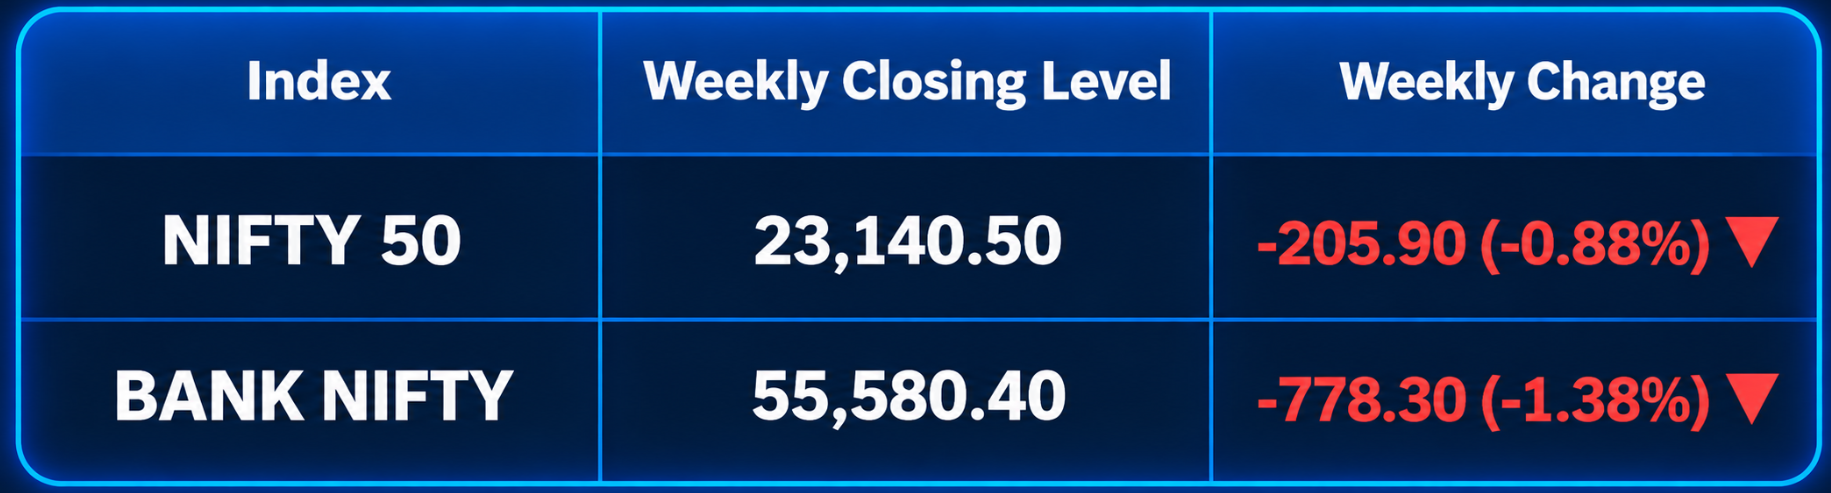
Indian equity markets ended another volatile week in the red, with the benchmark indices recording their seventh consecutive weekly decline, extending the longest weekly losing streak since 2020. The Nifty 50 declined 205.90 points (-0.88%) to close at 23,140.50, while the Sensex fell 399.22 points (-0.54%) to end at 73,895.74. The Bank Nifty slipped 778.30 points (-1.38%) to close at 55,580.40.
The Nifty traded between 23,020.95 and 23,489.00 during the week, reflecting continued volatility. Markets initially found support from easing crude oil prices and bargain buying, but Thursday's sharp sell-off erased the week's gains as crude surged, U.S. Treasury yields remained elevated and financial stocks came under pressure. Friday saw a partial recovery, with value buying in banking, auto and realty stocks helping benchmarks rebound from the week's lows.
The upcoming week from September 28 to October 2, 2026 will have only four trading sessions, as NSE and BSE will remain closed on Friday, October 2 for Mahatma Gandhi Jayanti. Tuesday, September 29 will also be important because it is the monthly F&O expiry for Nifty, Bank Nifty and stock derivatives.
Weekly Market Review.
Market Summary: Sensex & Nifty 50 Performance
Monday September 21: Indian markets began the week on a positive note as easing crude oil prices encouraged bargain buying. The Nifty gained 67.90 points (+0.29%) to 23,414.30, while the Sensex jumped 564.03 points (+0.76%) to 74,858.99. Bank Nifty gained 0.20% to 56,470.65. Pharma and Realty were among the stronger sectors, although FII selling continued.
Tuesday September 22: Markets reversed course, with the Nifty declining 85.30 points (-0.36%) to 23,329.00 and the Sensex falling 329.91 points (-0.44%) to 74,529.08. IT stocks led the weakness despite Brent crude easing to around $99 per barrel. Fourteen of the 16 major sectors ended lower, while Coal India bucked the trend following a brokerage upgrade.
Wednesday September 23: Markets staged a recovery as easing crude oil prices and positive global cues supported sentiment. The Nifty gained 117.80 points (+0.50%) to 23,446.80, while the Sensex rose 299.17 points (+0.40%) to 74,828.25. Bank Nifty gained 333.35 points (+0.59%) to 56,548.90. Metal, FMCG and financial stocks supported the recovery, while IT remained weak.
Thursday September 24: Markets witnessed their steepest single-session decline in around 10 weeks. The Nifty plunged 383.70 points (-1.64%) to 23,063.10, while the Sensex crashed 1,247.71 points (-1.67%) to 73,580.54. Bank Nifty fell 1.96% to 55,438.50. Surging crude oil, elevated U.S. Treasury yields and concerns surrounding proposed insurance commission rules triggered broad-based selling, with all 16 major sectoral indices ending lower.
Friday September 25: Markets recovered from Thursday's sharp fall. The Nifty gained 77.40 points (+0.34%) to 23,140.50, while the Sensex rose 315.20 points (+0.43%) to 73,895.74. Bank Nifty added 141.90 points (+0.26%) to 55,580.40. Auto, Realty, Consumer Durables and Financial Services led the recovery, while IT and Pharma remained under pressure.
Week-on-week: Nifty declined 205.90 points (-0.88%) to 23,140.50, Sensex fell 399.22 points (-0.54%) to 73,895.74, while Bank Nifty dropped 778.30 points (-1.38%) to 55,580.40.
Share Market Live News: The Big Macro Triggers This Week
1. Nifty Records Seventh Consecutive Weekly Decline
Despite recoveries on Monday, Wednesday and Friday, the Nifty ended the week 0.88% lower at 23,140.50, marking its seventh consecutive weekly decline and extending its longest weekly losing streak since 2020.
The index touched a weekly low of 23,020.95, making the 23,000 zone an important near-term technical level. On the upside, repeated selling around the 23,400–23,500 region indicates that the market will need a sustained move above this zone to improve the short-term structure.
2. Crude Oil & Middle East Developments Remain Critical
Crude oil remained one of the biggest drivers of Indian equities. Brent eased below $100 earlier in the week as hopes of diplomatic progress supported sentiment, but subsequently surged toward $105 per barrel, contributing to Thursday's sharp market sell-off.
By Friday, Brent had eased again to around $102.86 per barrel, down roughly 2.23%, providing some relief to domestic equities.
For India, sustained crude prices above $100 remain important because of their potential impact on inflation, the rupee, corporate margins and the external balance.
3. Global Bond Yields Keep Markets on Edge
Elevated global bond yields continued to weigh on risk sentiment during the week. Thursday's sharp sell-off coincided with the U.S. benchmark Treasury yield climbing to its highest level since 2007, alongside the spike in crude oil prices.
Markets remain sensitive to expectations surrounding further U.S. monetary tightening, particularly after the Federal Reserve's recent rate increase. Higher global yields can also increase pressure on emerging-market capital flows.
4. India VIX Spikes Before Cooling on Friday
Volatility increased sharply during Thursday's market decline, with India VIX jumping 22.76% to 12.70 as broad-based selling hit domestic equities.
Friday's recovery helped volatility cool substantially, with India VIX ending at around 12.16, down 4.16% for the session.
Although volatility remains relatively contained in absolute terms, Thursday's spike showed how quickly risk sentiment can change amid crude oil, bond-yield and geopolitical developments.
5. Sector Rotation Remains Highly Selective
Sector performance remained highly volatile during the week. Thursday saw all 16 major sectoral indices decline, before selective buying returned on Friday.
On Friday, sector performance showed recovery in domestic cyclicals and financial pockets:
- Consumer Durables: +0.95%
- Realty: +0.92%
- Auto: +0.89%
- Financial Services: +0.56%
- FMCG: +0.40%
- Metal: +0.35%
- Energy: +0.21%
- Pharma: -0.10%
- IT: -0.17%
Top Nifty Gainers & Losers Last Week
Top Gainers (1-Week Performance)
- COAL INDIA: +3.95% | ₹426.10
Coal India emerged as the strongest Nifty performer for the week. The stock received support after a brokerage upgrade earlier in the week and displayed relative strength even as the broader market declined. Reuters reported a 3.2% rise on Tuesday alone following the upgrade. - ITC: +2.55% | ₹269.00
ITC remained resilient through the week's volatility and ended among the strongest Nifty constituents, supported by relative strength in defensive consumer names. - ETERNAL: +2.49% | ₹335.00
Eternal outperformed the benchmark during the week and remained one of the stronger large-cap consumer-internet stocks despite broad market volatility.
Top Losers (1-Week Performance)
- BHARTI AIRTEL: -5.70% | ₹1,785.40
Bharti Airtel witnessed sharp profit booking during the week after outperforming in the previous week. The stock was already among the prominent losers on Monday, when it declined more than 3%. - TRENT: -5.48% | ₹2,669.30
Trent remained under sustained selling pressure and significantly underperformed the broader benchmark during the week. - INFOSYS: -4.87% | ₹1,000.20
Infosys was pressured by persistent weakness across the IT sector. Technology stocks remained under pressure during multiple sessions amid concerns over demand and earnings outlook.
Institutional Activity: FIIs vs. DIIs
Institutional flows remained sharply divergent during the week, with heavy FII selling being countered by strong DII buying support. Foreign Institutional Investors (FIIs) recorded cumulative net outflows of approximately ₹11,490.03 crore during the week. The highest FII selling was witnessed on Thursday at ₹5,027.36 crore, followed by Monday at ₹3,809.99 crore and Friday at ₹3,693.93 crore. FIIs remained net sellers in four of the five trading sessions, while Wednesday saw net buying of ₹1,617.45 crore.
Domestic Institutional Investors (DIIs) maintained their strong buying momentum, registering total net inflows of around ₹16,398.15 crore during the week. The highest DII buying was recorded on Monday at ₹4,120.07 crore, followed by Thursday at ₹4,301.18 crore and Friday at ₹2,838.17 crore. DIIs remained consistent net buyers across all five trading sessions.
Overall, combined institutional flows stood at approximately ₹4,908.12 crore of net inflows, highlighting the strength of domestic institutional participation despite substantial foreign selling. Persistent FII outflows kept sentiment cautious, while sustained DII buying helped absorb selling pressure and provided support to the broader market.
Market Outlook & Nifty Prediction for September 28 – October 2, 2026
Nifty enters the upcoming week at 23,140.50 after recording its seventh consecutive weekly decline.
The weekly chart shows the index continuing to face selling pressure, with this week's high restricted to 23,489 while the low slipped to 23,020.95. This makes 23,000–23,050 the most important immediate support zone going into the new week.
A sustained break below 23,000 could expose the index towards 22,800 and 22,600, while a recovery above 23,400–23,500 would improve the short-term structure and could open the way towards 23,700–23,800.
Expected range: 22,800 – 23,800
Support:
23,050–23,000 (immediate support zone)
22,800–22,600 (next major support)
Resistance:
23,400–23,500 (immediate resistance)
23,700–23,800 (major hurdle)
Bank Nifty:
55,300–55,000 support, 56,000–56,200 immediate resistance and 56,650–56,700 major resistance.
Key triggers:
(1) Crude oil and Middle East developments will remain among the biggest global triggers, especially with Brent still trading above $100 per barrel;
(2) U.S. Treasury yields and global rate expectations will remain important for emerging-market sentiment and foreign institutional flows;
(3) FII selling, DII support and the rupee will remain key domestic liquidity indicators. USD/INR was around 95.81 at the end of Friday;
(4) September F&O expiry on Tuesday, September 29 could increase volatility as Nifty, Bank Nifty and stock monthly derivatives expire;
(5) RBI liquidity management will remain in focus. The central bank is scheduled to conduct another ₹25,000 crore bond sale on September 28 as it works to reduce excess banking-system liquidity.
(6) The week will be shortened by the October 2 Gandhi Jayanti market holiday, leaving only four trading sessions.
(7) Technically, Nifty holding above 23,000 or reclaiming 23,400–23,500 could determine the next directional move.
Strategy: Maintain a selective approach while Nifty remains below the 23,400–23,500 resistance zone. The 23,000 level is the key downside pivot after being tested during the week. Rather than chasing short-term rebounds, traders can watch for confirmation around these levels. Coal India, ITC and Eternal showed relative strength this week, while IT and select consumer/telecom names remained under pressure.
Stocks to Watch & Investment Opportunities
Five stocks showing notable relative strength, momentum or important price action going into the holiday-shortened week:
- COAL INDIA
Coal India gained 3.95% during the week to ₹426.10, making it the strongest Nifty performer. The stock also received support from a brokerage upgrade earlier in the week. - ITC
ITC gained 2.55% during the week to ₹269.00, displaying defensive relative strength despite the broader Nifty declining almost 0.9%. - ETERNAL
Eternal advanced 2.49% to ₹335.00 for the week and remained resilient through the sharp Thursday market correction. - AXIS BANK
Axis Bank was one of Friday's strongest large-cap banking names, gaining around 2% as financial stocks recovered from Thursday's heavy sell-off. Continued strength could provide support to Bank Nifty around the crucial 55,000–55,300 zone. - HCL TECHNOLOGIES
HCL Tech was among Friday's stronger Nifty stocks even as the broader IT sector remained under pressure. The stock is worth tracking for signs of relative strength if the IT index stabilises after its recent weakness.
💡 Pro-Tip: Want a real-time technical analysis for these stocks? Ask LiMo, our AI co-pilot, for an instant buy/sell rating.
Discover Investment Opportunities with Liquide
Available on both Google Play Store and Apple Appstore, Liquide offers up-to-date market analysis, expert recommendations and real-time insights to guide your investment decisions.
Download the Liquide App today and enhance your financial journey.
Disclaimer: The information provided in this article is for informational and educational purposes only and does not constitute financial, investment or trading advice.
Stock, commodity and currency markets involve significant risk. Readers are strongly advised to consult with their financial advisors before making any investment decisions.
For a detailed Disclaimer, please visit our website https://liquide.life/