Weekly Review & Indian Stock Market Prediction (Sep 21st – Sep 25th, 2026)
Nifty declined 0.22% WoW to 23,346.40, extending losses for the sixth week amid global uncertainty and FII selling. HDFC Life, HCL Tech and Bharti Airtel gained, while TCS, Titan and Coal India declined. Full recap & outlook for September 21–25.
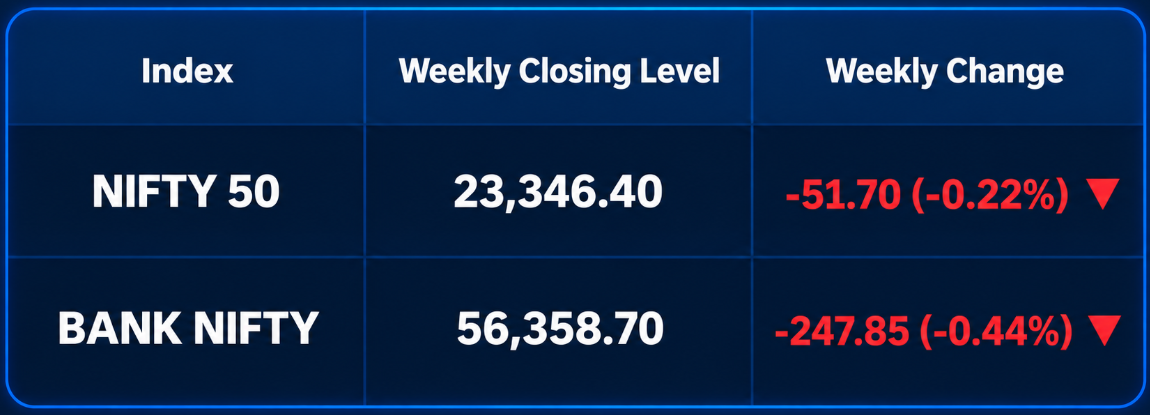
Indian equity markets ended another volatile, holiday-shortened week in the red, with the benchmark indices recording their sixth consecutive weekly decline. The Nifty 50 declined 51.70 points (-0.22%) to close at 23,346.40, while the Sensex fell 486.80 points (-0.65%) to end at 74,294.96. The Bank Nifty slipped 247.85 points (-0.44%) to close at 56,358.70.
The Nifty traded between 23,116.10 and 23,592.85 during the week, reflecting sharp intraday volatility. Elevated crude oil prices, continued geopolitical tensions in the Middle East, higher global bond yields and persistent foreign institutional selling kept sentiment cautious. However, bargain buying and easing crude prices helped the market recover from Tuesday's lows toward the end of the week. Reuters reported that this was the longest run of weekly losses for Indian equities since 2020.
The week had only four trading sessions, as NSE and BSE remained closed on Monday, September 14, for Ganesh Chaturthi. The upcoming week from September 21–25, 2026 is scheduled to be a normal five-session trading week, with the next NSE equity-market holiday falling on October 2.
Weekly Market Review.
Market Summary: Sensex & Nifty 50 Performance
Monday September 14: Indian stock markets remained closed for Ganesh Chaturthi, with trading resuming on Tuesday.
Tuesday September 15: Markets witnessed a sharp sell-off as the Nifty plunged 279.50 points (-1.19%) to 23,118.60, while the Sensex fell 777.94 points (-1.04%) to 74,003.80. Bank Nifty declined 1.43% to 55,794.80. Realty, Metal, Auto, Energy and financial stocks came under heavy pressure, while IT was the only major sector to close higher.
Wednesday September 16: Markets staged a recovery, with Nifty gaining 99 points (+0.43%) to 23,217.60 and Sensex rising 332.63 points (+0.45%) to 74,336.40. Bank Nifty outperformed with a 0.89% gain to 56,292.40, supported by FMCG, PSU Bank and Financial Services stocks, while IT witnessed profit booking.
Thursday September 17: Nifty extended its recovery, adding 53 points (+0.23%) to 23,270.60, while Sensex ended almost flat at 74,314.59. Bank Nifty declined 0.42% to 56,055.75. Pharma, Realty, Auto and Metal stocks supported the market, while banking and Energy stocks remained under pressure. Investors also digested the US Federal Reserve's 25-basis-point rate hike.
Friday September 18: Markets ended mixed, with Nifty rising 75.80 points (+0.33%) to 23,346.40, while Sensex slipped 19.63 points (-0.03%) to 74,294.96. Bank Nifty gained 302.95 points (+0.54%) to 56,358.70. Metal, Realty, Energy and Financial Services led the gains, while IT, Consumer Durables and FMCG remained weak.
Week-on-week: Nifty declined 51.70 points (-0.22%) to 23,346.40, Sensex fell 486.80 points (-0.65%) to 74,294.96, while Bank Nifty slipped 247.85 points (-0.44%) to 56,358.70.
Share Market Live News: The Big Macro Triggers This Week
1. Nifty Records Sixth Consecutive Weekly Decline
Despite recovering from Tuesday's lows, Nifty ended the week lower at 23,346.40, marking its sixth consecutive weekly decline.
The index tested a weekly low near 23,116, but buying emerged around the 23,100–23,200 zone. However, the index continues to trade below the important 23,600–23,700 resistance area, keeping the broader technical structure cautious. Reuters noted that this was the longest weekly losing streak for Indian equities since 2020.
2. Crude Oil & Geopolitical Risks Remain Key Market Drivers
Elevated crude oil prices remained one of the biggest concerns for Indian equities during the week. Brent traded above $100 per barrel for much of the period as Middle East tensions continued to create supply uncertainty.
Oil prices eased towards the end of the week, providing some relief to domestic equities, but crude remains an important risk factor for inflation, the rupee and India's external balance.
3. US Federal Reserve Raises Interest Rates
The US Federal Reserve raised its policy rate by 25 basis points, taking the federal funds rate range to 3.75%–4.00%.
The decision, combined with elevated global bond yields, continued to weigh on emerging-market sentiment and foreign institutional flows into Indian equities. Markets will now closely track further commentary around the global rate trajectory.
4. India VIX Cools After Early-Week Spike
India VIX rose sharply to around 13.43 on Tuesday as markets witnessed heavy selling, but volatility eased substantially over the remaining sessions.
By Friday, India VIX closed at 11.385, falling 7.36% during the session and roughly 7.3% from the previous week's closing level of 12.285.
The decline in volatility indicates that immediate fear reduced as the market recovered from Tuesday's lows, although macro risks remain elevated.
5. Sector Rotation Remains Highly Selective
Sectoral participation remained mixed through the week, with 10 of the 16 major sectors ending lower on a weekly basis, according to Reuters. Insurance stocks were notable outperformers, while individual IT, consumer and energy names remained volatile.
On Friday, sector performance showed a clear recovery in cyclical and financial pockets:
- Metal: +1.51%
- Realty: +1.19%
- Energy: +1.05%
- Financial Services: +0.76%
- Pharma: +0.49%
- Auto: -0.11%
- FMCG: -0.23%
- Consumer Durables: -0.43%
- IT: -1.03%
Top Nifty Gainers & Losers Last Week
Top Gainers (1-Week Performance)
- HDFCLIFE: +3.95% | ₹550.95
HDFC Life emerged as the strongest Nifty performer during the week. Insurance stocks attracted buying interest on expectations of healthy sector growth and improved earnings transparency under the evolving accounting framework. Reuters also highlighted the strong weekly performance in HDFC Life and SBI Life. - HCLTECH: +3.58% | ₹1,249.30
HCL Technologies remained one of the stronger IT names for the week. The stock benefited from the sharp technology-sector rebound early in the week, although profit booking returned across IT counters later. - BHARTI AIRTEL: +3.40% | ₹1,893.30
Bharti Airtel displayed strong relative strength compared with the broader market and remained among the leading Nifty performers for the week.
Top Losers (1-Week Performance)
- TCS: -4.35% | ₹2,105.00
TCS remained under pressure as profit booking returned to IT stocks during the latter half of the week. Selling in Tata Group companies also intensified on Friday. - TITAN: -4.21% | ₹4,798.50
Titan witnessed sustained selling pressure and underperformed the benchmark as consumer-related large caps remained volatile. - COAL INDIA: -3.87% | ₹409.90
Coal India remained among the weakest Nifty stocks for the week despite some recovery in the broader Energy sector on Friday.
Institutional Activity: FIIs vs. DIIs
Institutional flows remained divergent during the week, with persistent FII selling being countered by strong DII buying support. Foreign Institutional Investors (FIIs) recorded cumulative net outflows of approximately ₹7,619.69 crore during the week. The highest FII selling was witnessed on Thursday at ₹3,208.76 crore, followed by Tuesday at ₹2,977.86 crore and Wednesday at ₹2,032.61 crore. FIIs remained net sellers in three of the four trading sessions, while Friday saw a reversal with net buying of ₹599.54 crore.
Domestic Institutional Investors (DIIs) maintained their strong buying momentum, registering total net inflows of around ₹11,231.72 crore during the week. The highest DII buying was recorded on Wednesday at ₹3,908.23 crore, followed by Thursday at ₹3,617.75 crore and Tuesday at ₹2,686.05 crore. DIIs remained consistent net buyers across all four trading sessions, with Friday also recording purchases worth ₹1,019.69 crore.
Overall, combined institutional inflows stood at approximately ₹3,612.03 crore, reflecting continued strength in domestic institutional participation despite significant foreign selling during most of the week. While persistent FII outflows kept market sentiment cautious, sustained DII buying provided important support and helped absorb foreign selling pressure across the broader market.
Market Outlook & Nifty Prediction for September 21 - 25, 2026
Nifty enters the upcoming week at 23,346.40 after recording its sixth consecutive weekly decline.
The weekly chart indicates that the index continues to face selling pressure below the 23,600–23,700 zone. At the same time, repeated buying interest around 23,100–23,200 makes this the key immediate support area to monitor.
A sustained break below 23,100–23,200 could expose the index towards 23,000 and 22,800, while a recovery above 23,600–23,700 would improve the short-term structure and open the possibility of a move towards 23,900–24,000.
Expected range: 23,000 – 24,000
Support:
23,200–23,100 (immediate support zone)
23,000–22,800 (next major support)
Resistance:
23,600–23,700 (immediate resistance)
23,900–24,000 (major hurdle)
Bank Nifty:
55,750–56,000 support, 56,800–57,200 immediate resistance and 58,000 major resistance.
Key triggers:
(1) Crude oil prices and Middle East developments will remain crucial, particularly if Brent again moves sharply above the $100–105 zone;
(2) Global bond yields and the post-Fed interest-rate outlook will influence foreign flows and emerging-market risk appetite;
(3) FII selling, DII buying and rupee movement will remain important indicators for domestic liquidity;
(4) The NSE IPO closes on September 21, with its listing scheduled for September 24, making primary-market liquidity and the listing response important domestic triggers;
(5) Technically, Nifty sustaining above 23,600–23,700 or breaking below 23,100–23,200 could determine the next directional move.
Strategy: Maintain a cautious and selective approach while Nifty remains below the 23,600–23,700 resistance zone. Rather than aggressively chasing rebounds, traders can wait for confirmation around key support and resistance levels. Insurance, selected Financial Services and Telecom stocks continue to display relative strength, while IT remains highly stock-specific and volatile.
Stocks to Watch & Investment Opportunities
Five stocks from Healthcare, Banking, Energy, Infrastructure and Metal sectors with specific catalysts and strong momentum for the week ahead:
- HDFC LIFE
HDFC Life was the week's strongest Nifty performer, gaining 3.95%. Insurance stocks continued to attract interest amid expectations of healthy sector growth and greater earnings transparency. - HCL TECHNOLOGIES
HCL Tech gained 3.58% during the week, displaying relative strength despite significant volatility in the IT index. The stock remains worth tracking if technology stocks stabilise after Friday's selling. - BHARTI AIRTEL
Bharti Airtel gained 3.40% for the week and remained one of the strongest large-cap performers despite weakness in the benchmark indices. - HDFC BANK
HDFC Bank rebounded strongly on Friday, gaining 2.52%, helping Bank Nifty recover above 56,300. Sustained strength in the stock could be important for Bank Nifty's attempt to reclaim the 56,800–57,200 zone. - ADANI PORTS
Adani Ports gained 4.93% on Friday, emerging as the session's top Nifty gainer. Continued momentum in infrastructure and commodity-linked stocks makes the counter important to track during the coming week.
💡 Pro-Tip: Want a real-time technical analysis for these stocks? Ask LiMo, our AI co-pilot, for an instant buy/sell rating.
Discover Investment Opportunities with Liquide
Available on both Google Play Store and Apple Appstore, Liquide offers up-to-date market analysis, expert recommendations and real-time insights to guide your investment decisions.
Download the Liquide App today and enhance your financial journey.
Disclaimer: The information provided in this article is for informational and educational purposes only and does not constitute financial, investment or trading advice.
Stock, commodity and currency markets involve significant risk. Readers are strongly advised to consult with their financial advisors before making any investment decisions.
For a detailed Disclaimer, please visit our website https://liquide.life/